Defined-outcome, income and option-based strategies are increasingly crossing product boundaries as ETFs adopt techniques traditionally associated with structured products.
The convergence between structured products and ETFs is accelerating as defined-outcome, covered-call and autocallable strategies move across product wrappers.
A defined outcome only counts if you can actually deliver it, and that is what methodology design is really about - Karan Sood, Vest Financial
Recent product launches illustrate the trend. First Trust has expanded its range of structured and option-based ETFs this year, including three single-stock target income ETFs linked to Tesla, Apple and Nvidia in August and a covered-call silver-focused ETF in July. In February, it launched an autocallable ETF providing synthetic exposure to autocallable strategies on broad US equity indices, hedged by BNP Paribas, J.P. Morgan and Citi. Vest Financial acts as portfolio manager on all these new products.
First Trust's move into autocallables followed a broader expansion of the format across the ETF market. In November 2025, the firm filed for its first autocallable ETF in collaboration with Vest Financial, joining a group of ETF providers developing similar offerings.
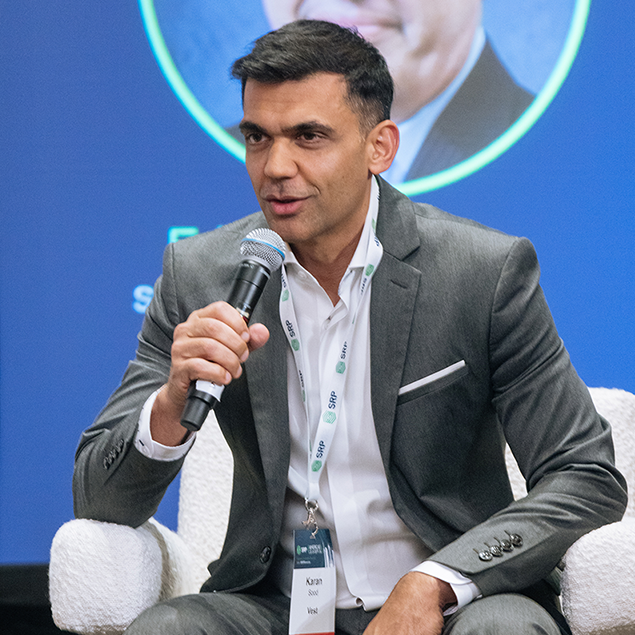
For Karan Sood (pictured), chief executive officer at Vest Financial, the increasing use of similar derivatives-based methodologies across ETFs, structured notes and indexed annuities represents the natural evolution of products that have historically operated in separate markets.
“I have spent most of my career at the seam between these structures, first as a structurer on a bank derivatives desk and, for more than a decade, designing funds,” he said.
“The convergence you describe feels less like a new trend than the natural result of each wrapper borrowing what the others do well.”
Sood points to the different characteristics of each structure. Structured notes can deliver precisely defined payoffs but expose investors to issuer credit risk, while indexed annuities combine defined outcomes and guarantees with the constraints of an insurance wrapper.
ETFs, meanwhile, offer intraday liquidity, transparency and tax efficiency without unsecured exposure to a single issuer.
The development of derivatives infrastructure has helped bring these characteristics closer together. The use of FLEX options within 1940 Act funds allows ETFs to replicate features traditionally associated with structured products, including defined buffers, specific strikes and capped upside. Collateralised swaps can also introduce contingent coupons and bespoke reference assets into the ETF wrapper.
Room for innovation
“The methodology becomes the product; the wrapper becomes the interface,” Sood said, adding that he expects the next phase of innovation to focus on expanding the range of outcomes available to investors.
“We launched the first buffer fund in 2016, though the Target Outcome methodology behind it came first,” he said. “For years the harder part was explaining why a defined outcome was worth having at all. Now buffer and option-based strategies are close to a standard tool in many advisor portfolios.”
Sood identifies income as another area where structured product features are increasingly moving into ETFs, including contingent income strategies traditionally associated with autocallable notes.
“The swaps behind it are marked daily, which limits the counterparty risk that remains,” he said.
However, he cautions that the expansion of derivatives-based ETFs should not come at the expense of transparency.
“The next wave that lasts will not be the most intricate,” he said. “It will be the products that stay legible, do what they say across different markets, and behave well long after launch.”
Sood also sees index methodology as central to whether a defined-outcome strategy delivers as intended.
“A defined outcome only counts if you can actually deliver it, and that is what methodology design is really about,” he said.
According to Sood, fund structures introduce frictions that can create a gap between the outcome specified at the beginning of a period and the result ultimately received by investors, including transaction costs, funding mismatches, rebalancing drag and operational costs.
Transparency, rules-based construction and robustness are therefore key considerations when designing strategy indices, said Sood.
“Rules over discretion, because outcomes that depend on in-the-moment judgment tend to fail exactly when they are needed most,” he added.
The relationship between structured products and ETFs is increasingly two-way. Sood argues that structured products have provided the ETF market with a framework for designing investments around a specific outcome rather than starting with an asset and adding derivatives afterwards.
At the same time, the ETF wrapper brings liquidity and transparency to strategies traditionally delivered through notes.
“Structured products taught the industry how to define and deliver outcomes, and their techniques seeded this wave of defined-outcome ETFs,” Sood said. “The ETF taught it how to deliver them with transparency and liquidity, without asking investors to trust a single balance sheet.”
“The interesting work now is bringing those two lessons together in one product.”
| This Q&A is published in full as a preview of the SRP Custom & Strategy Report 2026, which includes selected extracts from the interview. |
Do you have a confidential story, tip or comment you’d like to share? Contact Us | SRP (structuredretailproducts.com)