Three senior lawyers from Mayer Brown examined defined outcome products, with emphasis on ETF structures, taxation, regulation, disclosure and bespoke indices during the SRP Americas 2026 Conference in Scottsdale, Arizona.
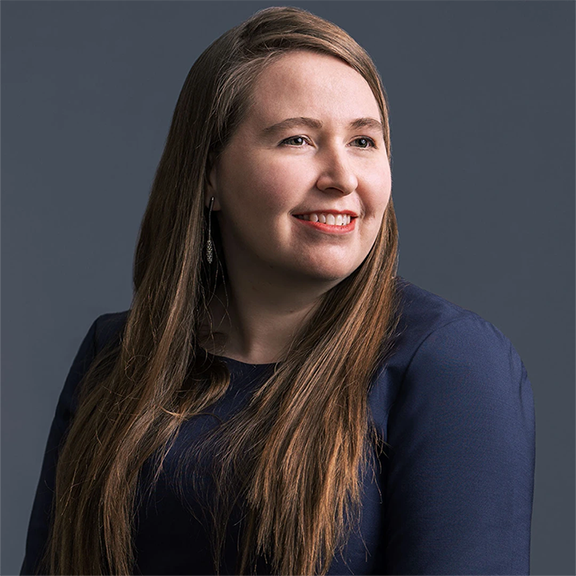
Defined outcome products come in many different shapes and sizes. Best known is the exchange-traded funds (ETFs) variant, however they come in many other flavours, particularly structured notes, but also separately managed accounts (SMAs), fixed-indexed annuities (FIA) and registered index-linked annuities (Rilas), according to Marla Matusic (pictured), partner at Mayer Brown,
We are [increasingly] seeing structured product type payoffs and all of their varieties showing up in defined outcome ETFs - Maria Matusic
“These are products that provide equity exposure […] the [defined outcome] version that is most popular is leverage exposure, generally to a cap with some downside protection,” Matusic, partner at Mayer Brown, told the audience in Scottsdale.
The variety of structures has been expanding, including Phoenix structures providing periodic coupons as well as dual directional products.
“We are [increasingly] seeing structured product type payoffs and all of their varieties showing up in defined outcome ETFs,” said Matusic.
According to Brennan Young, partner at Mayer Brown, defined outcome ETFs are mostly treated as regulated investment companies for tax purposes.
“ETFs generally seek regulated investment company status to obtain pass-through treatment and avoid entity-level tax,” said Young who highlighted the importance to achieve regulated investment company (RIC) status.
“You are taxed like a mutual fund were income and gains can pass through and keep their character.”
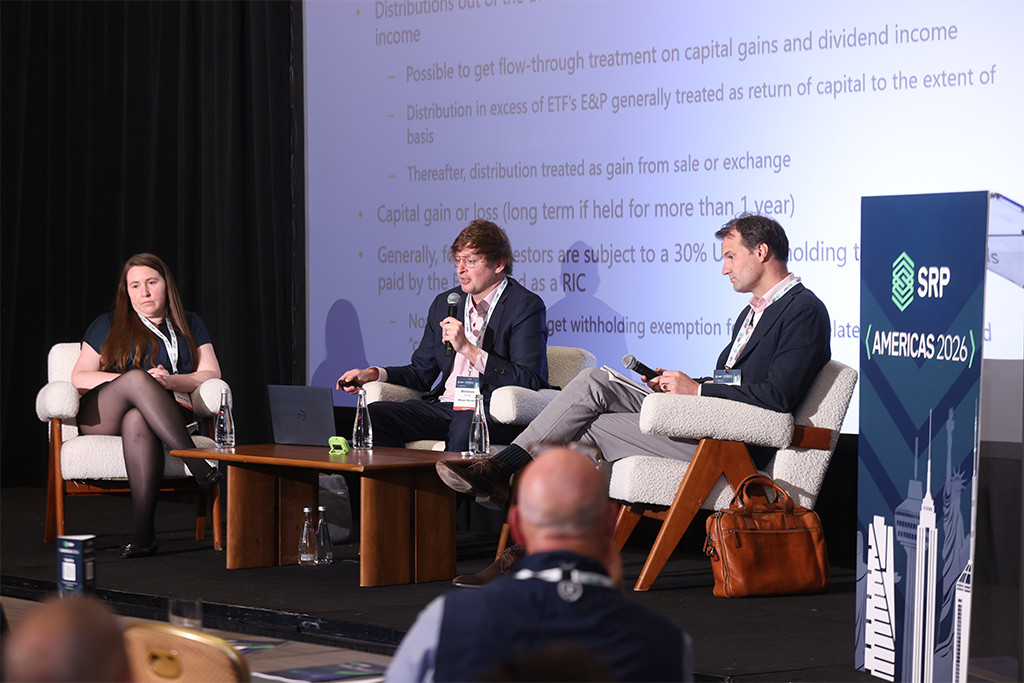
Left to right: Marla Matusic, Brennan Young and Remmelt Reigersman
Requirements include domestic corporation status, Investment Company Act registration, a 90% gross-income test, quarterly diversification tests and distribution of taxable income.
“At least 90% of the taxable income of the of the ETF has to come from dividends, interests, payments with respect to security loans, gains from sale or distribution of stock,” said Young.
Treasuries are generally suitable for the relevant tests, while the treatment of equity swaps is less explicit.
“The last category, other income from securities transactions like options, futures, forwards, does a lot of the heavy lifting when it comes to these defined outcomes,” Young added.
Remmelt Reigersman, partner at Mayer Brown grouped structured notes into principal-protected notes (type one), non-principal-protected notes without periodic coupons (type two), and non-principal-protected notes with periodic coupons (type three).
Type one notes are generally treated as debt; type two notes resemble forwards or prepaid forwards; and type three notes may be treated as a single derivative or debt plus a put option.
“To compare and contrast over the years, there are so many different economic payout profiles and flavours in structured notes,” he said.
ETF option strategies may replicate note payoffs without comparable income accrual, potentially producing long-term capital gains.
Remmelt Reigersman
Reigersman identified the continued use of tax code Section 852(b)(6), which allows ETFs to distribute appreciated securities in-kind without triggering capital gains taxes at the fund level, as an area of anticipated scrutiny.
“852(b)(6) is a code section that allows an ETF to redeem out a shareholder in exchange for appreciated property without paying tax,” he said.
Reigersman cited that if an ETF has an Apple stock that has appreciated, it can redeem out shareholders and not trigger gain needs yet.
“If you don’t trigger the gain, you don’t have to make a distribution because, as Brennan [Young] said, you need to distribute at least 90% of your income […] but if you don’t trigger gain income, you don’t have to distribute anything, so 852(b)(6) is a pretty powerful tool to manoeuvre with,” he said.
Matusic provided background on SEC Rule 6c-11, a regulation that allows qualifying, transparent ETFs to operate without needing a costly and slow individual exemptive order from the SEC.
“Prior to rule 6c-11 for ETFs, you had to get individual relief letters, which was a very long process, […] and perhaps not what you want to do all the time. This rule allowed a more streamlined process,” she said.
The rule only applies to fully transparent ETFs, index-based ETFs.
“When we say fully transparent ETFs, we are talking about understanding all the terms […] some of the compliance obligations, if you are not able to disclose all your constituents, you would not be able to comply with all the other requirements,” Matusic concluded.
Do you have a confidential story, tip or comment you’d like to share? Contact Us | SRP (structuredretailproducts.com)