The index provider is seeing stronger demand for higher-volatility equity strategies as structured notes, insurance products and structured ETFs increasingly share the same index architecture.
Nasdaq’s custom index offering now spans a broad range of investment strategies and product applications, from Dorsey Wright momentum indices used in structured products and ETFs and Adaptive Volatility strategies deployed in structured ETFs and QIS, to Victory and Dividend indices supporting income products and the Nasdaq CTA Artificial Intelligence Index providing thematic AI exposure.
Today, clients are increasingly looking at higher-volatility equity-only approaches, reflecting changing market conditions and investor appetite - Richard Macari
The Nasdaq-100 also serves as a foundation for customised QIS implementations across structured notes, FIAs, RILAs and ETFs, illustrating how a common index architecture can increasingly be adapted to different investment wrappers and investor outcomes.
Nasdaq is seeing a shift in demand for custom and strategy indices, with equity-only and higher-volatility approaches gaining ground as structured products, insurance solutions and structured ETFs increasingly converge around common index methodologies.
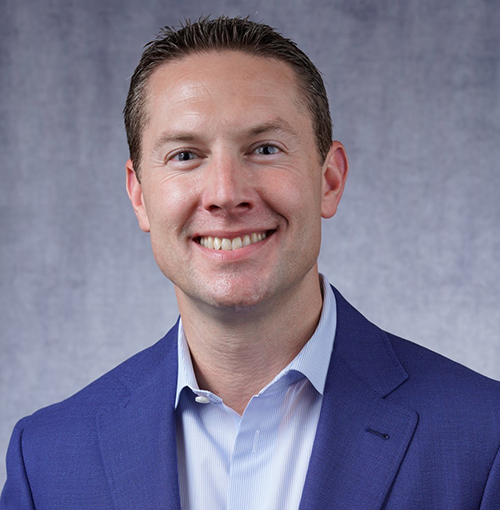
Richard Macari (pictured), head of insurance and bank index solutions at Nasdaq, says the underlying demand for custom indices has remained relatively consistent, but the types of strategies being requested have changed with market conditions.
“A few years ago, most conversations centered on low-volatility, multi-asset strategies designed for lower interest rate environments,” Macari says. “Today, clients are increasingly looking at higher-volatility equity-only approaches, reflecting changing market conditions and investor appetite.”
Nasdaq is also seeing greater interest in strategies that dynamically adjust volatility according to market regimes rather than targeting a fixed level. Higher-volatility equity strategies have gained share relative to the multi-asset volatility-control mandates that previously dominated.
Volatility-controlled indices have nevertheless continued to perform an important role, particularly during the second quarter of 2026, demonstrating that demand remains dependent on market conditions and the objectives of the end product.
One methodology, multiple wrappers
The bigger development, according to Macari, is the convergence of investment wrappers.
Nasdaq is increasingly working with banks on index suites where a single methodology can support structured notes, insurance products such as fixed indexed annuities (FIAs) and indexed universal life (IUL) policies, as well as structured ETFs.
“Rather than designing separate indices for each channel, the same underlying index can now be adapted across multiple products,” he says. “That allows investors to access similar investment ideas through different wrappers depending on their objectives.”
Insurance remains an important area of demand, with volatility-controlled strategies seeing strong interest in IUL products across Asia Pacific. The same methodologies can also be deployed across domestic and international markets.
The convergence is also influencing the development of structured ETFs, where Nasdaq is working with a limited number of banking partners on methodologies that can be deployed across the growing segment.
“We see it as expanding the market rather than fragmenting it,” Macari says. “Structured ETFs create additional opportunities for investment banks, ETF issuers and index providers.”
Nasdaq expects further launches during the second half of the year, with the focus on developing deeper partnerships rather than maximising the number of counterparties.
Equity takes the lead
Equity strategies now account for the majority of custom index demand, according to Macari.
“Overall, we would estimate demand currently runs at roughly two or three equity-only mandates for every multi-asset request,” he says.
Gold's strong performance last year has maintained some interest in diversified strategies, while uncertainty around fixed income has reduced demand for some multi-asset approaches. Multi-asset indices nevertheless retain a role for clients seeking diversification.
Custom strategies are increasingly being used alongside, rather than instead of, traditional benchmarks such as the Nasdaq-100 and S&P 500.
“Traditional benchmarks will always remain core building blocks,” Macari says.
Within insurance, a benchmark can sit alongside a custom strategy offering different participation rates or enhanced return potential. Nasdaq is also seeing increased demand from registered index-linked annuities (RILAs) for higher-volatility custom equity strategies designed to generate additional alpha within the product structure.
Decrement strategies cross the Atlantic
The evolution of custom indices is also creating greater cross-border exchange of ideas.
Decrement indices have been embedded in European structured product design for years but have seen slower adoption in the US. Macari says they are increasingly being used in US structured ETFs, although they have not become part of the investment culture to the same extent.
“Rather than one market following another, we're seeing ideas moving in both directions,” he says. “European experience with decrement strategies is influencing the US, while US developments in QIS and insurance are being adopted across Europe and Asia.”
The result is a more fluid market in which index methodologies developed for one product or geography can increasingly be adapted for another.
AI adds another layer
Artificial intelligence is also beginning to influence index development, although Macari describes the technology's role as being at an early stage.
Some strategies incorporate AI directly through stock selection or thematic exposure, while AI is also being used to assist portfolio allocation and accelerate the development of methodologies and supporting documentation.
Nasdaq's exposure to many of the companies driving AI adoption is also supporting demand for its broader equity benchmarks and new thematic strategies.
James Caparosa, Director, Index Sales at Nasdaq, says the trend is particularly relevant to insurance carriers looking to provide policyholders with exposure to long-term AI themes.
“Carriers are increasingly asking how they can future-proof their product line-ups by giving policyholders exposure to long-term AI trends rather than individual companies,” Caparosa says.
The focus is therefore shifting away from selecting individual AI winners towards broader thematic exposure to companies and technologies expected to drive future market growth.
From index provider to development partner
The process of creating custom strategies is becoming more collaborative, with Nasdaq working more closely with banks and distribution partners from the outset.
“Innovation is no longer about an index provider presenting a finished product,” Macari says. “The most successful strategies are developed jointly with distribution partners through an iterative process that refines both the investment methodology and the client proposition.”
Nasdaq has added resources to support bank partnerships and co-develop new strategies, reflecting the increasingly complex requirements of product manufacturers.
For Macari, the opportunity is therefore broader than simply creating more custom indices. It is about developing investment frameworks that can be deployed across multiple channels.
“Major benchmarks will remain the foundation of the market, but demand for customized strategies across insurance, structured products and structured ETFs continues to grow,” he says.
Equity strategies are expected to remain at the centre of innovation, alongside more sophisticated volatility-management techniques and increasingly complex payoff structures embedded within indices.
“The opportunity is not simply about creating more custom indices,” Macari says. “It's about delivering customized outcomes through multiple distribution channels using a common investment framework.”
Caparosa sees the same convergence at the outcome level.
“The market is increasingly focused not just on creating custom indices, but on delivering customized investment outcomes across different wrappers, whether that is structured notes, insurance products or ETFs,” he says.
“The same underlying investment ideas can increasingly be adapted across multiple channels, allowing product manufacturers and distributors to meet different investor needs.”
| This Q&A is published in full as a preview of the SRP Custom & Strategy Report 2026, which includes selected extracts from the interview. |
Do you have a confidential story, tip or comment you’d like to share? Contact Us | SRP (structuredretailproducts.com)