Market share for products linked to single equity indices increased by more than 20% YoY.
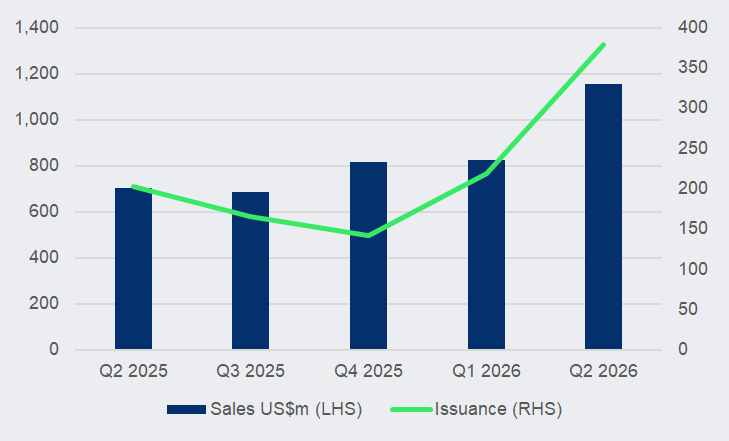
An estimated US$1.2 billion was collected from 379 publicly offered structured products that struck during Q2 2026 in Central and Eastern Europe (CEE) markets covered by SRP (Czech Republic, Hungary, Poland and Slovakia).
Sales reached their highest levels since Q2 2017, when US$1.3 billion was collected from 238 products
Sales reached their highest levels since Q2 2017, when US$1.3 billion was collected from 238 products.
Volumes increased by around 40% compared to the previous quarter; year-on-year (YoY) they were up by 65%.
Issuance was up by 160 products quarter-on-quarter (QoQ) and increased by 175 YoY.
CEE region: issuance and sales volumes (US$m) by quarter
Source: SRP
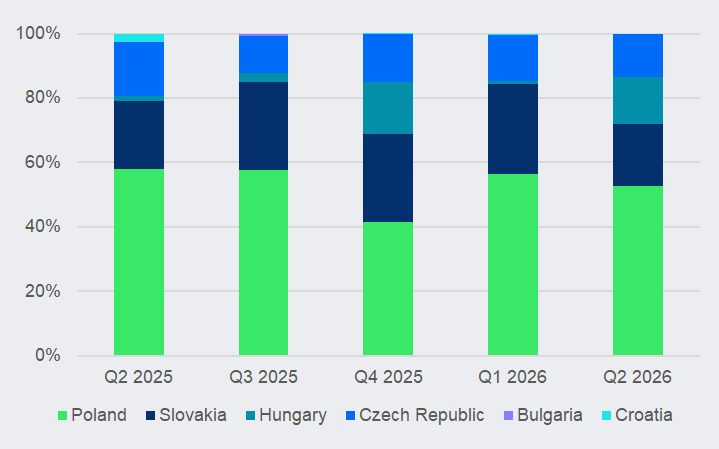
Some 53% of the total volumes in the region were invested in products issued in Poland, down three percentage points compared to the 56% market share in Q1 2026 and a five percentage points decrease YoY.
Slovakia captured 19% market share (Q1 2026: 28%; Q2 2025: 21%), while the highest increase – both QoQ and YoY – was registered by Hungary: from one percent in Q2 2025 and Q1 2026 to 15% this time around.
CEE region: market share by country
Source: SRP
Market share for Czech Republic, at 14%, remained stable QoQ (Q2 2025: 17%).
Best sellers
Société Générale’s Autocall Note (344995EN/26.4) was among the best-selling products in the quarter, according to SRP data. The four-year structure, which offered access to the Eurostoxx Banks Index registered sales of HUF8.5 billion (US$27.6m) in Hungary.
Another product that sold well, this time in the Czech Republic, was the J.P. Morgan-issued PDCP 5.25% Deep Barrier Plus, which was listed in Luxembourg for an issued amount of CZK490m (US$23.6m).
In Poland, Credit Agricole Bank Polska collected PLN78.5m (US$21.6m) with Swiatowe Indeksy II, a six-year digital issued via BNP Paribas Issuance BV that offered access to a basket comprising the Stoxx Europe 600 and S&P 500, while VÚB gathered €12.3m (US$14.4m) in Slovakia with its four-year Max Long Certifikát on the Stoxx Europe 600 Real Estate.
Best performers
The top 10 best performing products in the region were all express certificates linked to single stocks that offered annualised coupons from 15.6% upwards.
Of these, the Raiffeisen Bank International (RBI)-issued Express Certificate on the share of ARM Holdings, which was distributed in Poland via Dom Inwestycyjny Xelion, expired early in June – at the third opportunity – returning 138.10% of capital after 18 months (24.08% pa).
Another Express Certificate, this time issued via Unicredit and linked to Micron Technology, redeemed early after six months, returning 110% of the nominal investment to investors in Poland while the US dollar-denominated Express Plus Certificate on ASML Holding returned 115.97% – after one-year – to investors in the Czech Republic.
The latter was one of 24 express certificates linked to the Dutch multinational chipmaker that autocalled in the quarter – their average annualised return was 11.8%.
In total, 107 products expired early in the region, returning an average annualised coupon of 10.73%. Most early redemptions were seen in the Czech Republic (79 products), followed by Slovakia, Poland (12 each) and Hungary (four).
Issuers
Nineteen issuers were active in the region during the quarter (Q1 2026: 18; Q2 2025: 19). They were a combination of local financial institutions and European/US investment banks.
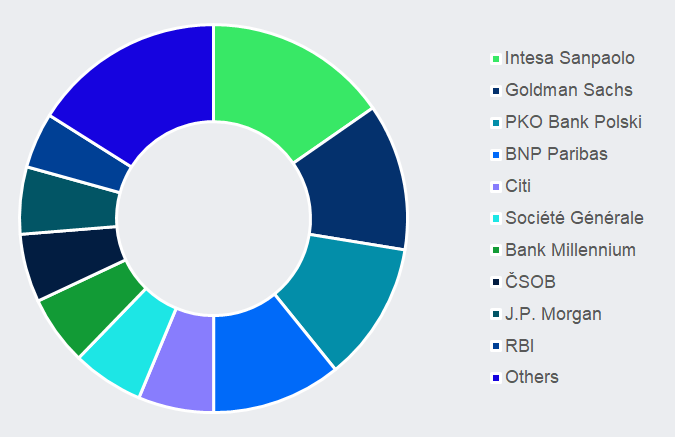
CEE region Q2 2026: top 10 issuer groups – market share by sales volume
Source: SRP
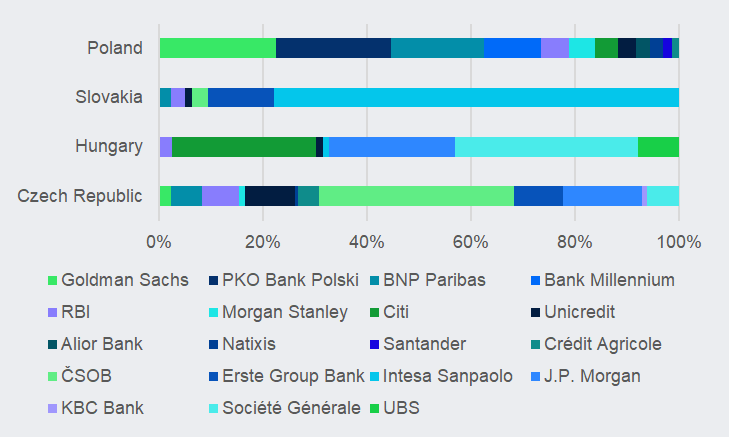
Intesa Sanpaolo, the parent company of VÚB, was the number one issuer with a 15% share of the CEE market. The bank issued seven capital protection products linked to equities and single equity indices. Of these, six were distributed via VÚB in Slovakia and the remaining product, Max Long Quanto Certificates on Euro iStoxx 50 Precious and Industrial Metal Miners Tilted NR Decrement 5% Index, was available via CIB Bank to retail investors in Hungary.
Goldman Sachs claimed 12% market share that was achieved from 18 products that were available via local distributors in Poland (14), Czech Republic (three) and Slovakia (one).
PKO Bank Polski, in third, held 11.6% market share from seven products that were sold via its own branch network in Poland.
CEE region Q2 2026: issuer group by market
Source: SRP
RBI and Unicredit were the only issuers with a presence in all four CEE markets in the quarter under review. The former issued eight products in the Czech Republic, four in Poland and three each in Hungary and Slovakia.
Meanwhile, Unicredit was the most prolific issuer by issuance – by some distance. The Italian multinational banking group issued almost 200 products in the Czech Republic alone – nearly all express plus certificates linked to single names. A further 33 express plus certificates were targeted at investors in Slovakia, including seven tied to the share of Deutsche Bank, while the bank also issued certificates in Poland (three) and Hungary (two).
Asset class, underlyings
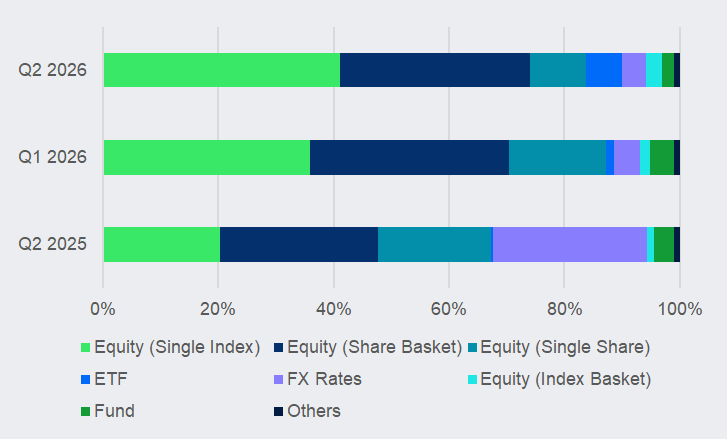
The region continued its focus towards structures linked to a single equity index: 66 products collected US$475m – the equivalent of a 41% market share, up five percentage points QoQ and an increase of 21 percentage points YoY.
The Eurostoxx 50 and Eurostoxx Banks were the most frequently used (12 products each) followed by Solactive AI Data & Robotics EUR AR Index (four), Solactive Souverainete Europeenne 20 Decrement 5% Index and Stoxx Europe 600 Basic Resources (three each).
CEE region: asset classes – market share by sales volumes
Source: SRP
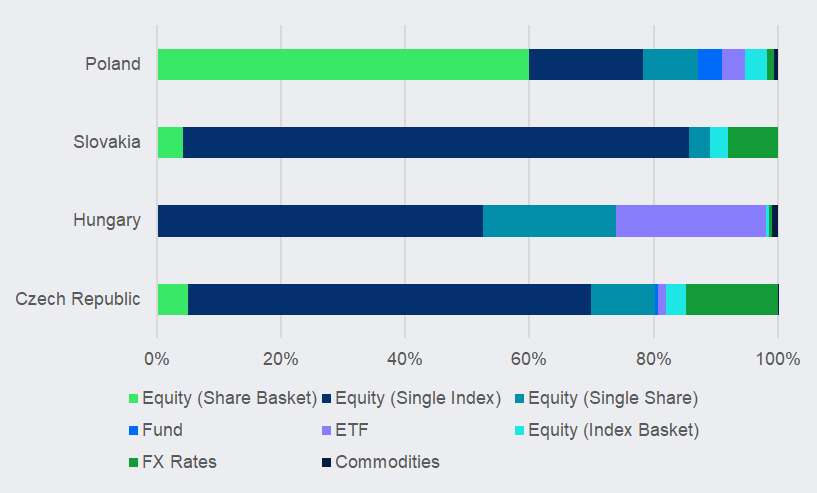
Another 35 products, worth an estimated US$380m and mostly targeted at investors in Poland (27) were linked to a basket of equities. Their market share, at 33%, remained stable QoQ and was up by six percentage points YoY.
Some 237 products were linked to a single stock (10% market share vs 17% in Q1 2026 and 20% in Q2 2025). The share of Novo Nordisk B was the most used (43 products) ahead of ASML Holding (28), Advanced Micro Devices (25) and Rheinmetall (15).
CEE region Q2 2026: asset class by market
Source: SRP
Products linked to exchange-traded funds (ETFs) gathered six percent market share from six products issued across the region, including the BNPP-issued Twin-Win Jaderná energie 4/2026, which offered access to the Global X Uranium ETF.
Structures linked to FX rates – 17 in total, split between the Czech Republic (10), Poland (five), Hungary and Slovakia (one each) – registered a significant YoY decrease: from 27% in Q2 2025 to four percent this time around (Q1 2026: four percent).
Payoffs
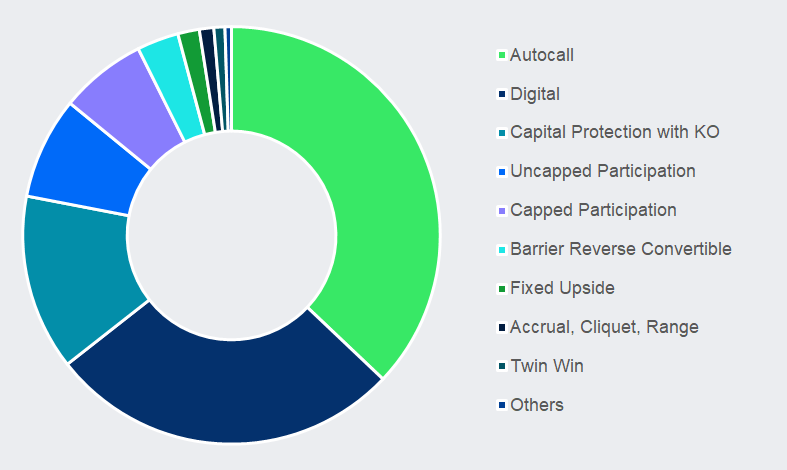
The autocall payout stood out: its market share, at 37%, increased by 10 percentage points compared to the previous quarter and was also up from to the 25% registered in Q2 2025.
CEE region Q2 2026: payoffs – market share by sales volume
Source: SRP
Digitals and capital protection with knock out gathered 27% and 14% market share, respectively, while products offering uncapped participation in the underlying asset held eight percent market share.
Capital protection, investment terms
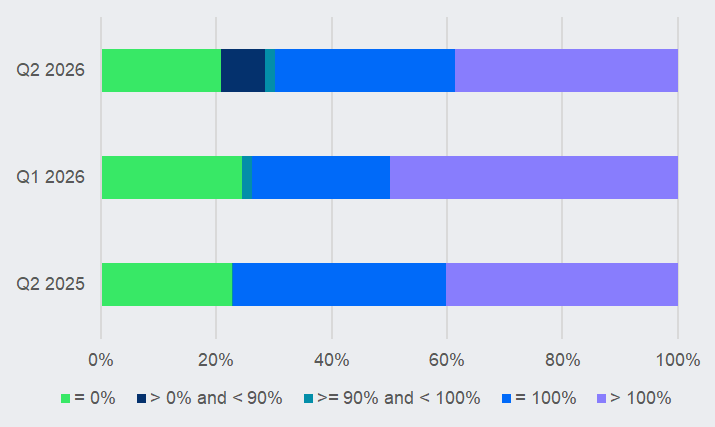
Investors in the region remain cautious in the balance, with 72% of sales for the quarter invested in products that protect at least 90% of the nominal invested (Q1 2026: 75%; Q2 2025: 77%).
The highest capital return was provided by Obligacje z Ochroną Kapitału w USD, a certificate distributed by Erste Bank Polska in collaboration with Natixis Structured Issuance which returns at least 106% of capital after two-years. It collected PLN55.8m during subscription and offered access to the shares of Santander and BNP Paribas.
CEE region: capital protection – market share by sales volume
Source: SRP
The average tenor was 4.10-years, an increase compared to 3.81-years in the previous quarter and also significantly higher compared to 3.63-years average registered in Q2 2025.
Looking ahead
Some 98 structured products with strike dates in the third quarter of 2026 have been added to the SRP database to date. Of these, 45 products are targeted at investors in Poland; 38 are aimed at investors in the Czech Republic; 14 at investors in Slovakia; and two at investors in Hungary.
In addition, 103 products are due to mature in Q3 2026, providing potential rollover opportunities worth an estimated US$715m.
A further 180 products have an autocall observation during the quarter.
Image: Zerophoto/Adobe Stock
Do you have a confidential story, tip or comment you’d like to share? Contact Us | SRP (structuredretailproducts.com)
Disclaimer: While SRP's aim is to provide accurate and up-to-date information, the data provided is gathered from third parties. SRP does not take responsibility for the accuracy of the data and will not be held liable for any errors or omissions contained in the information provided. The information and data included on SRP's market reports uses sources believed to be reliable. SRP assumes no liability or responsibility for the quality, content, accuracy or completeness of the information, text, graphics, links and any other items contained on this report.