The next phase of defined-outcome ETFs is shifting from replicating structured notes to engineering systematic payoffs that can operate continuously within an ETF wrapper.
The rapid growth of defined-outcome ETFs is opening a new phase in structured-payoff design, with autocall strategies emerging alongside more established buffered and protected products.
Structured notes just still have a massive… advantage from a customization standpoint - Bryan Bondoc, VegaShares ETFs
The market now comprises roughly US$70–80 billion across more than 400 defined-outcome ETFs, according to panel participants at SRP Americas 2026. Within the autocall segment, speakers cited more than 30 actively trading funds with around US$5 billion in assets, alongside more than 70 filings.
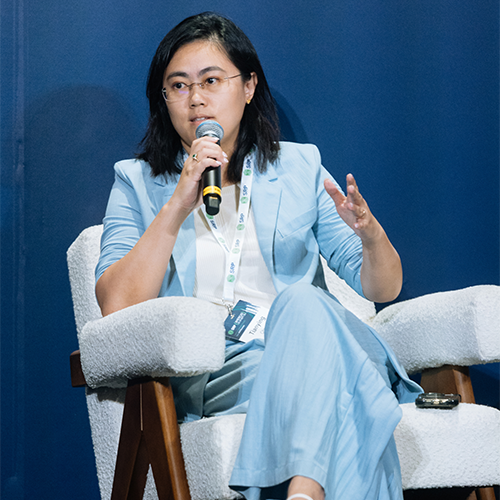
Moderated by Thabata Ribeiro Maly, head of structured solutions distribution at Morgan Stanley, the Index engineering I: ETF structured payoff design and replication layers panel brought together Bryan Bondoc, managing director at VegaShares ETFs, and Tianyin Cheng (pictured), head of products at MerQube, to examine how structured payoffs are being adapted for ETFs and where the two wrappers diverge.
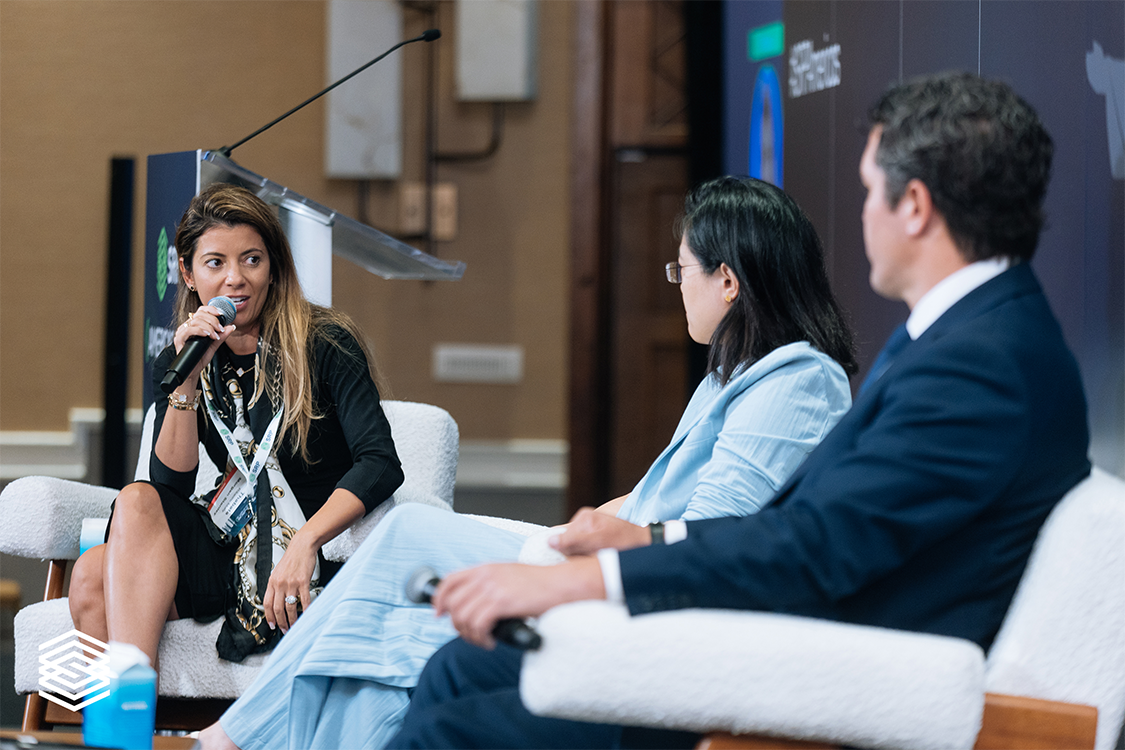
Left to right: Thabata Ribeiro Maly, Morgan Stanley; Tianyin Cheng, MerQube; and Bryan Bondoc, VegaShares ETFs.
From notes to systematic payoffs
Bondoc said the first generation of structured-payoff ETFs demonstrated that these strategies could work within an ETF, but the market has since moved towards more complex designs including autocalls.
The question now is less about replicating a structured note and more about engineering a payoff that works within an ETF.
“I personally don't see it as structured ETF, buffered ETF, replacement of structured notes,” Bondoc said.
Cheng said the shift involves moving from bespoke structured-product engineering towards systematic, option-based index engineering.
An ETF presents a different design challenge from a note. A note has defined issuance terms and a maturity date, whereas an ETF is effectively perpetual and must accommodate ongoing creations, redemptions and secondary-market trading.
The objective, therefore, is to translate the economic characteristics of a structured payoff into a systematic methodology that can operate continuously.
Left to right: Tianyin Cheng, MerQube and Bryan Bondoc, VegaShares ETFs.
Cheng identified three requirements: a pricing model aligned with market pricing, a properly designed index and portfolio, and reliable calculation infrastructure. Together, these can help investors understand the strategy while giving market makers greater confidence in pricing and providing liquidity.
Different wrappers, different uses
The panel rejected the idea that ETFs and structured notes necessarily compete for exactly the same assets.
Notes retain an important advantage in customisation, allowing advisors to tailor payoffs, terms and underlyings to individual client requirements. ETFs offer scalability, operational efficiency and easier integration into portfolio and model-based approaches.
“Structured notes just still have a massive… advantage from a customization standpoint,” Bondoc said.
ETF conversations can also shift the focus away from individual barriers and call features towards portfolio allocation, implementation, performance and taxation.
Cheng described the two markets as potentially complementary. Demand for a particular payoff in the note market can help establish whether an ETF version has an audience, while an ETF can subsequently make the strategy available to a broader investor base.
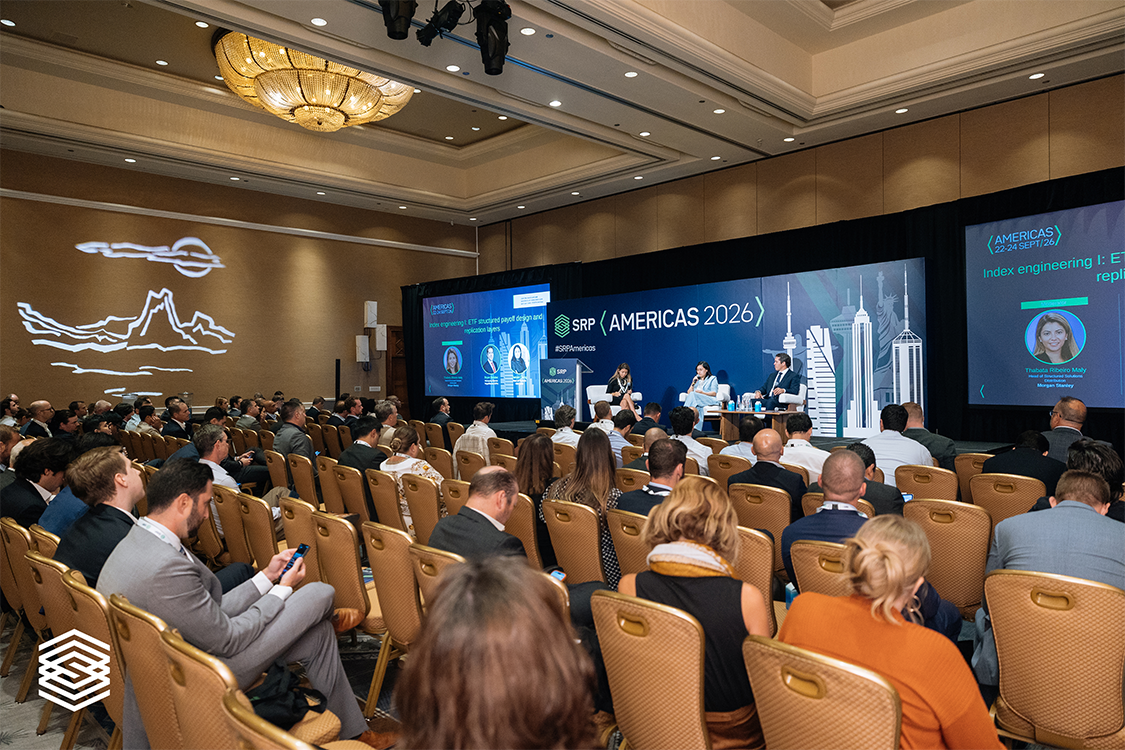
Left to right: Thabata Ribeiro Maly, Morgan Stanley; Tianyin Cheng, MerQube; and Bryan Bondoc, VegaShares ETFs.
The result could be a feedback loop between the two channels rather than a straightforward substitution of one wrapper for another.
Maly stressed that there is no universally preferable wrapper. The appropriate structure depends on the sponsor, implementation and intended investor.
Index versus portfolio replication
The panel examined two broad approaches to delivering a structured payoff through an ETF: using an index-based swap or holding a portfolio of individual swaps linked to notes.
An index-based approach can provide a systematic reference point for pricing and performance, while allowing the strategy to be back-tested across different market environments.
Cheng also highlighted the importance of frequent and reliable index calculations. The index needs to align with the level used to write the swap so that market makers can price the exposure consistently.
Bondoc cautioned against treating either approach as inherently superior.
An index can provide a more systematic, rules-based framework, while a portfolio of notes can offer greater flexibility and make greater use of a manager's expertise. The approaches can also produce different performance and tax outcomes.
“There's no right or wrong answer here… It's just making sure that you're understanding what the trade-offs are,” Bondoc said.
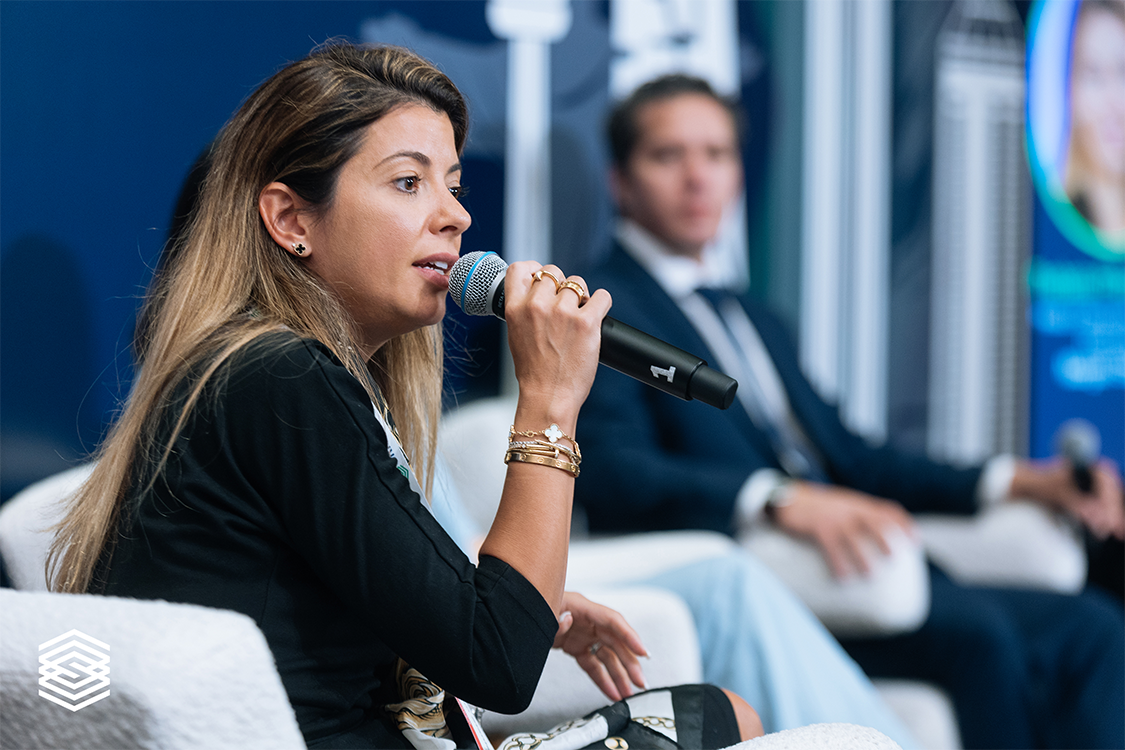
Left to right: Thabata Ribeiro Maly, Morgan Stanley; Tianyin Cheng, MerQube; and Bryan Bondoc, VegaShares ETFs.
The underlying credit exposure also differs. Structured notes carry the credit exposure of the issuing bank, while ETF structures commonly use swaps. Bondoc said the ETF swaps he was familiar with were generally fully collateralised, with VegaShares using US Treasuries as collateral.
Infrastructure becomes critical
As structured payoffs move into ETFs, scalability increasingly depends on the infrastructure supporting them.
Pricing, index calculation, rebalancing, market making and the creation-and-redemption mechanism all need to operate together.
The panel did not identify a specific capacity ceiling for options-based ETF strategies. Instead, Cheng emphasised the role of reliable index infrastructure in helping market makers price and trade the products, while Bondoc pointed to scalability and implementation as key reasons for choosing an ETF wrapper.
Investor use also varies by distribution channel.
Fee-based advisors may incorporate structured ETFs into model portfolios, while brokerage clients may use them for only part of a portfolio. The ETF therefore needs to be designed with its intended investor and portfolio role in mind.
More complex payoffs ahead
Innovation is now moving beyond the basic translation of note payoffs into ETFs.
Cheng pointed to features including memory mechanisms for autocalls, where a missed coupon can accumulate and potentially be paid later if the relevant conditions are met. She also highlighted more complex underlyings and basket structures, alongside improvements in pricing models that can support more sophisticated strategies.
Bondoc expects continued development in both payoff and index design but cautioned that not every note structure is suitable for an ETF.
Features such as memory coupons and no-call periods need to be considered differently when the underlying vehicle has no fixed maturity. Adding a new index methodology to a systematic payoff can also increase complexity for investors.
That places greater emphasis on how the strategy is engineered and communicated, rather than simply on the novelty of the payoff.
“Responsible innovation, responsible engineering, I think is very, very important,” Bondoc concluded.
Do you have a confidential story, tip or comment you’d like to share? Contact Us | SRP (structuredretailproducts.com)