The US manager says demand for autocallable ETFs is growing but cautions investors against comparing products by yield alone.
Calamos Investments has pointed to its capabilities in index design and execution after winning two prizes at the SRP Americas 2026 Awards. It warned, however, that autocallable ETFs with similar headline yields can carry very different risks.
A volatility-managed reference can behave differently from a conventional equity benchmark during sharp market moves - Jordan Rosenfeld
The US asset manager won Best Structured ETF Solution, while its Calamos Autocallable Growth ETF, CAGE, took Structured ETF Innovation of the Year at the awards held in Scottsdale, Arizona, on 23 September.
Calamos said the awards recognised its work in bringing autocallable payoffs, traditionally arranged through bilateral bank transactions, into an ETF. It launched its first autocallable income ETF, CAIE, in June 2025, and then later a Nasdaq-linked income fund and CAGE in April of 2026.
The manager mentioned that its approach usually depends on how the underlying indices are actually constructed and how the strategies are implemented through swaps. CAGE seeks long-term capital growth through exposure to a laddered portfolio of synthetic autocallable strategies linked to a MerQube volatility-managed index. Coupons are retained within the strategy, rather than paid out as regular income.
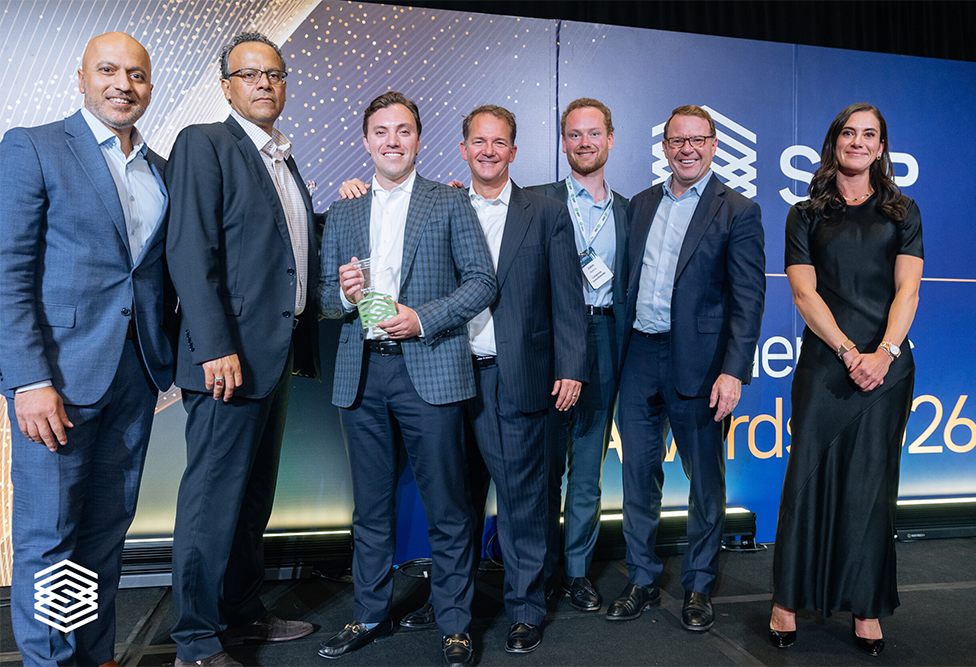
The Calamos team at the SRP Americas 2026 Awards in Scottsdale, Arizona on 23 Augustus. Third from left, Jordan Rosenfeld.
Calamos portfolio manager Jordan Rosenfeld highlighted the use of implied-volatility targeting in the firm’s flagship quantitative investment strategy (QIS) indices. He said the design seeks to capture the difference between implied and realised volatility, with less leverage than some comparable approaches. According to Rosenfeld, realised volatility in the underlying index has been more than five percentage points below the target.
The difference between CAGE and the income-oriented funds illustrates why the term autocallable ETF does not describe a single investment objective.
CAGE retains coupons within the strategy and seeks long-term capital growth, whereas Calamos’s income funds are presented as a way to generate cash flow. In either case, the investor is taking exposure to conditional payoffs whose results can change with the path of the underlying market.
The index used to determine those payoffs also matters. “A volatility-managed reference can behave differently from a conventional equity benchmark during sharp market moves, while swap execution determines how the strategy is implemented in the ETF,” said Rosenfeld. “These mechanics may be less visible than an advertised coupon, but they are central to assessing the risks.”
Rosenfeld warned against treating autocallable ETFs as interchangeable. “What’s under the hood is not the same,” he said, citing differences in volatility controls, underlying assets and exposure during market sell-off periods.
Demand grows as risks diverge
The awards come as assets in the autocallable ETF segment have grown rapidly. Calamos executives put total category assets at roughly US$6 billion and said the manager had raised around US$2 billion across its autocallable ETF range since launching CAIE in June 2025. They said demand for traditional structured notes remained strong alongside ETF growth.
The executive partially attributed demand to investors seeking retirement income and advisers looking for ways to generate portfolio cash flow. Rosenfeld also pointed to growth in fee-based advice and the ability to trade standardised structured strategies through an ETF. Some investors reinvest fund distributions, Rosenfeld said, especially when advisers expect range-bound or modest equity returns.
“Yield comparisons can also obscure the importance of barriers and observation dates,” added Rosenfeld. “An autocallable may pay a stated coupon only when its contractual conditions are satisfied, and a missed payment may or may not be recovered depending on the structure.”
In a worst-of basket, the weakest performer can drive the result even when the other reference assets have fared better.
“That makes the composition of the basket and the level of downside barriers just as important as the quoted income rate,” noted Rosenfeld. “An investor looking for reliable cash flow needs to consider periods without distributions, while one intending to hold the product over several years must also assess potential losses if markets fall sharply. The same headline yield can therefore describe quite different exposures.”
Rosenfeld warned that worst-of autocallable strategies can become more volatile when equities fall sharply. Unlike indices with explicit volatility controls, conventional equity-linked baskets may offer much less protection against rises in volatility during a sell-off. He urged investors to consider missed coupons and possible principal losses rather than focusing solely on advertised yields.
Calamos also launched the Calamos Least-Of Autocallable Income ETF (CAYN) on 26 October. The fund references the weakest performer among SPY, QQQ and IWM through a weekly ladder of synthetic notes with three-year maturities. Its coupon and principal barriers are set 30% below the relevant initial reference levels, and missed coupons can be recovered if the conditions are subsequently met. Investors, however, do remain exposed to principal losses. The fund was launched after SRP’s interview and has no significant live performance history.
Calamos is considering further additions to the range, including another total-return-focused QIS autocallable strategy and potentially one or two other products. Rosenfeld said the aim was to address different income and risk preferences rather than just introduce a large number of similar funds.
“We’re not trying to flood the zone,” he said. For advisers comparing products, Rosenfeld recommended examining historical and hypothetical stress scenarios alongside the advertised yield. “How you get there really matters,” he said.
| Calamos won the ‘Best Structured ETF Solution’ and ‘Structured ETF Innovation of the Year’ Awards at SRP Americas 2026. Click the link to view all the winners. |