The French bank expects issuance linked to its proprietary indices to exceed $13bn in 2026, with multi-asset and low-volatility strategies benefiting from demand for diversification and capital-protected structured products.
BNP Paribas ranked fifth in the US structured products market in August, selling 772 unregistered notes. The French bank has held its position as the highest-ranked non-US issuer in the top five since July, having overtaken J.P. Morgan in May with US$2.2 billion in sales to climb to second place in the league table. Since the start of 2026, BNP Paribas has consistently competed for this position.
The bank is also seeing growth in proprietary index strategies, with issuance across the segment expected to exceed US$13 billion in 2026, representing nearly five percent of the total US market, according to Samy Moffadel, head of RIA solutions at BNP Paribas, and Stanislas Mesland, QIS Americas head of FIAs and retail underlyings.
In September 2026, the BNP MAD 5 index ranked among the top FIA multi-asset indices, with a return of 5.88%, followed by the BNP Paribas Patriot Technology Index at 5.80%.
A version of the BNP MAD 5 index, the BNP Paribas Multi Asset Diversified X index (MADX), received the Index of the Year award, Structured Products, at SRP Americas 2026.
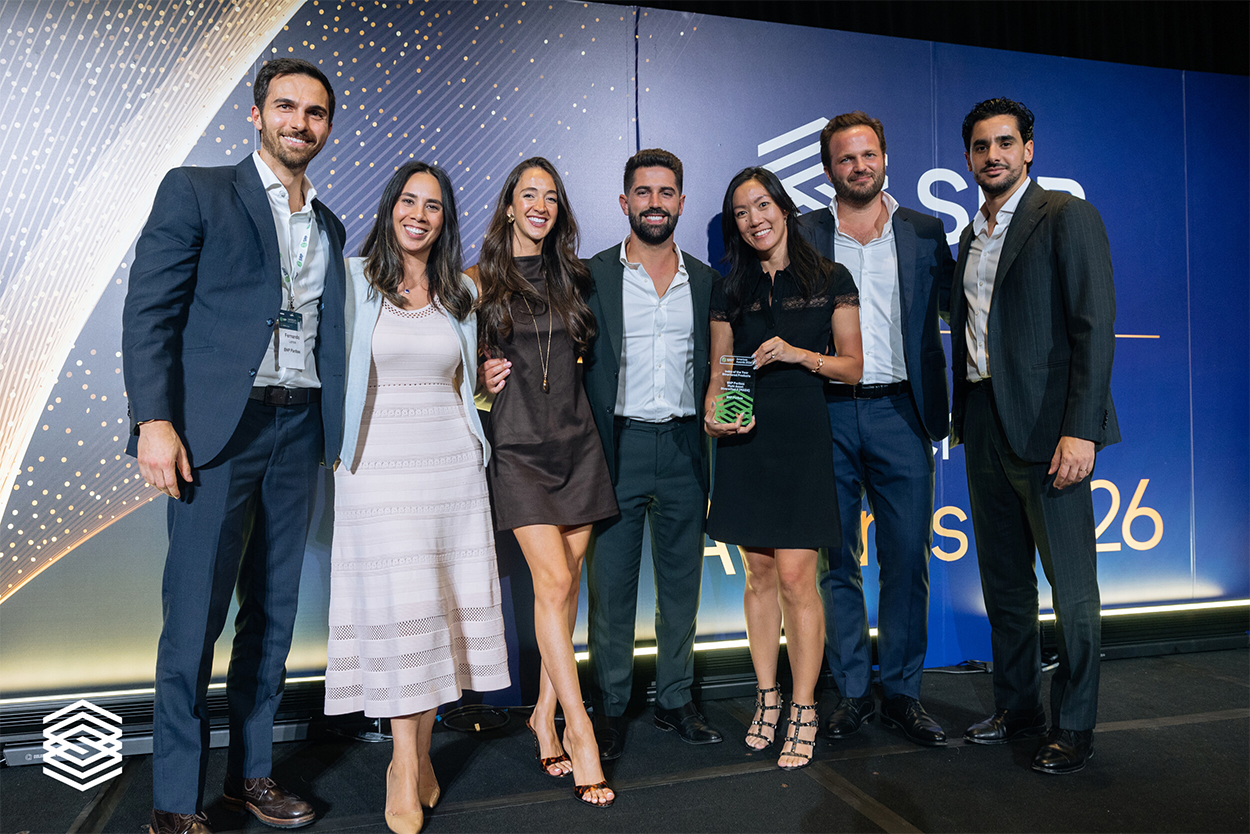
The BNP Paribas team at the SRP Americas 2026 Awards in Scottsdale, Arizona on 23 September.
Multi-asset strategies gain traction
The MADX builds on BNP Paribas’ flagship BNPIMAD5 index, which has more than 10 years of track record. The objective was to retain its diversified multi-asset exposure while adapting the strategy for autocallable principal-protected structures, a product category that has seen significant demand growth in recent years.
“The MADX provides allocation across three asset classes (bonds, equities, and commodities) and three regions (US, Europe, and Japan),” Mesland said.
The index uses proprietary trend and risk metrics indicators. A key difference from MAD5 is the addition of a second layer of trend indicators, which allows the strategy to deleverage following underperformance over the preceding six months, helping to mitigate sustained drawdowns.
Moffadel said the index’s diversified, all-in-one approach and ability to deliver an enhanced risk-return profile compared with equity-only indices had helped it gain traction. Its low volatility also makes it suitable for principal-protected structures, he added, with higher interest rates and market uncertainty supporting demand for these products.
Built on the same algorithm as MAD5, MADX uses a methodology that has delivered positive performance in eight of the past 10 years, according to Mesland.
“It is more relevant than ever in an environment where macro and geopolitical risks are driving the performance of the different asset classes, and at an accelerated pace,” he said.
The bank remains committed to this approach and has developed a range of solutions around it, Mesland added.
Proprietary indices
BNP Paribas expects issuance linked to its proprietary indices to grow across both low- and high-volatility strategies. The bank anticipates that its issuance in this segment in 2026 will be triple the level reported last year.
“In 2026, high-volatility issuances are expected to double compared to 2025 levels,” Mesland said. “However, low-volatility strategies, most of which are multi-asset based, are experiencing even more rapid growth.”
Higher interest rates are helping issuers offer more attractive terms, while demand is also increasing for strategies that diversify risk away from concentrated benchmarks, he added.
Moffadel said distributor feedback pointed to a growing divide in investor preferences. While some advisers remain positioned in AI-driven themes in pursuit of growth, others are becoming more cautious amid heightened uncertainty.
“This shift is reflected in the rising demand for defensive, capital-protected structures,” he said.
The current high-rate environment supports this trend by enabling issuers to offer enhanced terms.
Competitive landscape
BNP Paribas anticipates increased volumes in the fourth quarter, driven by potential autocall events, provided market conditions and leading proprietary indices remain stable.
Most products issued in the fourth quarter of 2025 with a one-year non-call period will reach their call dates over the next three months. The bank estimates that called volumes could exceed US$2.5 billion.
“The doubling of volumes year over year represents a highly impressive and sustained trend,” Mesland said.
The bank also sees ETFs as complementary to structured notes, with their adoption by advisers potentially widening the market for systematic strategies.
“While ETFs lack the level of customisation offered by notes, their widespread adoption by advisors significantly expands the addressable market,” Moffadel said.
Moffadel expects performance to be the main differentiator between market leaders and laggards, making underlying strategy design critical.
Mesland said the competitive landscape for proprietary strategies was changing as more issuers introduced their own versions across different categories.
“This gives distribution networks greater scope to compare performance, consistency and terms when selecting solutions for clients,” he said.
Historically, some networks had been reluctant to adopt proprietary strategies because of concerns about pricing opacity. As independent broker-dealers begin using these indices, BNP Paribas anticipates further expansion in the custom index market, favouring providers able to innovate and respond to client needs, Mesland said.
Image: Mesteban75/Adobe Stock